Private and hard-money lenders
Underwrite the borrower's record, not their résumé.
Every deed, lien and federal case behind a borrower's LLCs, in one record your credit team can check before you fund.

Borrowers send a schedule of real estate owned. You can't easily check it.
The schedule lists what the borrower chose to list. The county recorded everything else: the projects that ran long, the liens that never released, the lawsuits.
Every entity they borrow through.
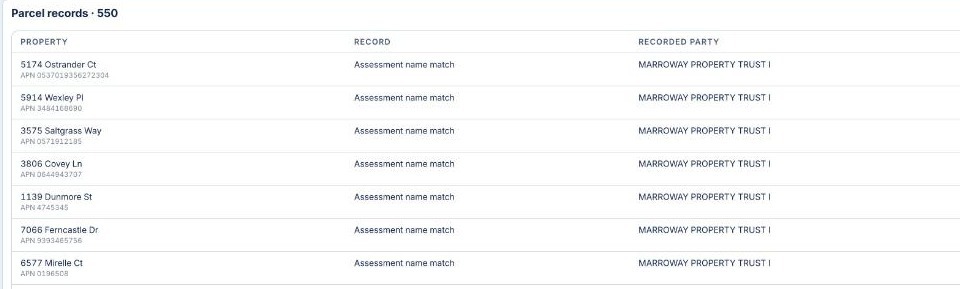
Borrowers buy each project in a new LLC. Tractline joins them back to one record, with every parcel, county and recording date.
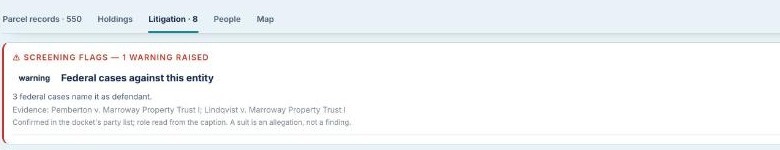
Liens and lawsuits before the draw.
Federal cases, unreleased liens and tax-lien certificates are raised as flags, with the docket or recording behind each one.
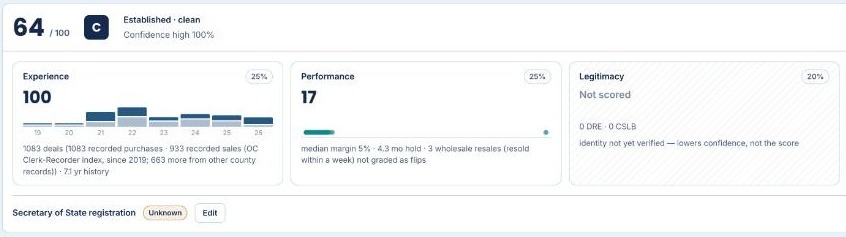
A grade your credit committee can read.
Experience, performance, legitimacy, risk and scale, each weighted and each traced to the records that moved it.
Questions the record answers
Where each answer shows up in the record, and the public source it comes from.
| Question | Where it shows |
|---|---|
| Has the borrower finished projects like this one? | Experience and performance |
| How long do their projects take? | Performance: median hold |
| Do they leave liens behind? | Risk flags |
| Are they being sued? | Litigation tab |
| Is the LLC in good standing? | Registration check |
How it fits your day
Run the borrower
Type the borrower or any LLC on the application.
Read the record
Deals, holds, liens and cases on one page.
Fund or ask
Clear the file, or ask the borrower about the exact gap.
Bring a borrower file.
We'll run the record with you before your next funding decision.